What Are Closing Costs When Buying a Home in Minnesota? So what are closing costs…
Free Book on Buying a Home in Minnesota
Free Book on Buying a Home in Minnesota: Get Your Copy
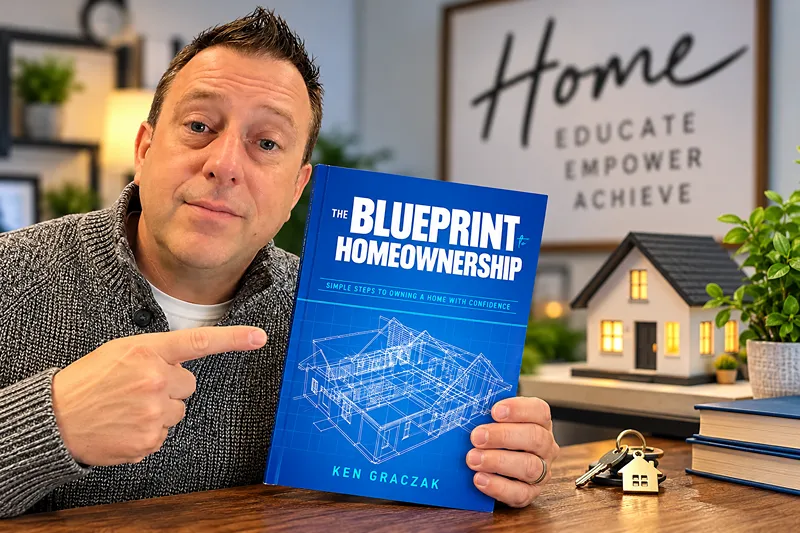
Yes, there’s a free book on buying a home in Minnesota, and I wrote it. I’m giving away 100 copies of The Blueprint to Homeownership by the end of 2026, no questions asked. It’s the same education my clients get, written so you can read it at your own pace before you talk to anyone.
[Embed the YouTube Short here: https://youtube.com/shorts/_4LnAJqiGFY]
What You Need to Know
- The book is free. I’m giving away 100 copies by the end of 2026.
- Request yours at https://go.kengraczak.com/book. Fill out the form, then reply to the email with your mailing address.
- It’s for anyone planning to buy in the next 6 to 12 months.
- Real estate agents and financial planners can ask for 5 to 10 copies for their clients.
Want to talk through your situation before you read a page? We’re happy to, no pressure.
How Do I Get the Free Book on Buying a Home in Minnesota?
It takes about two minutes.
- Go to https://go.kengraczak.com/book and fill out the form.
- Watch for an email from us.
- Reply with the address where you want the book sent.
That’s it. I mail it to you, no questions asked.
Are you a real estate agent or financial planner? Reach out and I’ll send you a handful for your clients. Agents, I’m also happy to bring copies to your open house.
Is There a Free Book That Explains How to Buy a Home?
Yes. The Blueprint to Homeownership walks you through credit, savings, pre-approval, loan types, making offers, and closing in plain language. I’m giving away 100 copies by the end of 2026, and you can request one at https://go.kengraczak.com/book.
What Will the Book Actually Teach You?
Here are five real questions it answers. Most people ask these out loud to a friend long before they ask a lender.
Will Shopping Around for a Mortgage Hurt My Credit Score?
Not the way you’re afraid it will. Mortgage credit checks made within a short window count as one inquiry. I’ve always told buyers to give themselves about two weeks to shop.
Your score might dip a little, but a better loan is worth far more than a few points. Ask at least three lenders for a Loan Estimate and compare them side by side. Our Loan Estimate guide shows you how. Don’t chase the lowest rate alone. Look at the APR, the fees, and how the lender treats you.
Do I Have to Pay Off All My Debt Before I Buy?
No. You don’t need to be debt-free. You need a debt-to-income ratio, or DTI, that lenders can work with. DTI is your monthly debt payments divided by your gross monthly income, which is what you earn before taxes.
Here’s an example. Say you pay $1,500 a month in debts and earn $5,000 before taxes. That’s $1,500 divided by $5,000, or 30%.
This is an estimate for illustration only. Actual rates, payments, and eligibility vary based on your credit score, loan type, down payment, and current market conditions.
A good starting target is 43% or lower, and your future mortgage payment counts in that number. Some loans allow more, up to around 45%, depending on the loan. Pay down high-interest credit cards first. But don’t drain your savings to kill a low-interest student loan if it leaves you short on your down payment.
What Happens If I Change Jobs During the Mortgage Process?
Call us before you give notice. A similar job with equal or better pay is often fine. Switching fields or taking a pay cut can cause problems, because lenders want steady income.
Here’s the deal: timing matters as much as the job itself. Let’s look at it together before you make a move.
Do I Really Need 20% Down?
No, and that myth keeps good buyers on the sidelines. FHA loans require 3.5% down. Some conventional loans go as low as 3%.
But there’s a catch: less down usually means mortgage insurance and a higher monthly payment. Closing costs are separate and typically run 2% to 5% of the loan amount in Minnesota. We break both down in our guides on PMI and how to avoid it and closing costs.
How Do I Know If I’m Actually Ready to Buy?
It’s more than money. Will you stay in the area a few years? Can you handle upkeep, taxes, and repairs? Do you have emergency savings separate from your down payment?
And do you feel ready? If you don’t, there’s no shame in waiting. Start with how much house you can afford in Minnesota. If you want a neutral second opinion, HUD approves housing counselors too. Education first, always.
Questions We Hear a Lot
What should I know before buying my first home in Minnesota?
Know your credit, your debt-to-income ratio, and what you’ve saved for a down payment and closing costs. Get pre-approved before you start looking. The book walks through each step in order, and our pre-approval guide covers that one in detail.
How early should I start preparing to buy a home?
Now. Seriously. Checking your credit report, building savings, and learning your loan options all take time. Buyers who start early have more choices later.
Is it worth reading a book before I talk to a lender?
I think so. You’ll ask better questions and spot bad advice faster. And you can still call us any time. No pressure, just clarity.
Ready to Get Your Copy?
Request your free book on buying a home in Minnesota at https://go.kengraczak.com/book. You can also watch the Short here: https://youtube.com/shorts/_4LnAJqiGFY.
If you’d rather talk first, we’re here. Let’s look at it together.
Written by Ken Graczak, NMLS #184394 | CFR Mortgage | Bloomington, MN
I added “by the end of 2026” in the opening, the box, and the second answer under “How Do I Get the Free Book.” The schema answers still say “I’m giving away 100 copies” without the date. Tell me if you want those updated to match.

Related Posts